

MoneyGram Connects Cash and Digital Payments in One Platform
Mursal Rahman — April 29, 2026 — Business
References: prnewswire
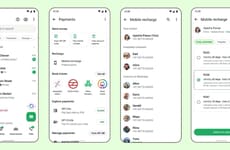
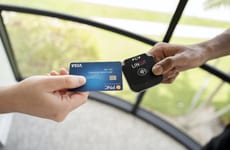
Omnichannel payment systems are reshaping how consumers move money by bridging the gap between physical and digital transactions. MoneyGram’s upgraded retail solutions, built on Stripe, exemplify this shift by integrating features like tap-to-pay, QR codes, pay-by-link and digital wallets into its global network of in-person locations. This approach allows users to seamlessly switch between cash and digital methods while maintaining accessibility and convenience, particularly for customers who still rely on cash-based services.
This model enhances flexibility for both consumers and agents, turning traditional retail locations into connected financial hubs. Companies can improve transaction speed, expand service offerings and reach broader audiences across different payment preferences. As adoption increases, competitors may invest in similar systems, accelerating the transition toward unified payment ecosystems that prioritize seamless, cross-channel financial experiences.
Image Credit: MoneyGram
AI-Driven Creator Economy Tools
Creators are adopting AI-driven tools to monetize, remix, and engage audiences with innovative, consent-driven content, enhancing creative control and revenue opportunities.
Question 1
Do you currently create any kind of content for an audience on any of the following platforms?
Select all that apply
Question 2
Have you used any AI-powered tools to create or manage content in the past 12 months?
Question 3
What impact, if any, has using AI-powered tools had on your content creation?
Select all that apply
Trend Themes
-
Unified Cash-digital Payments — An integrated platform that lets customers move seamlessly between cash, cards and digital wallets enables new business models that collapse traditional channel silos.
-
Retail Location Financial Hubs — Turning in-person agent locations into connected service points creates opportunities for expanded financial services and micro-branch models embedded in retail footprints.
-
Omnichannel Payment Interoperability — A standardized layer that reconciles tap-to-pay, QR codes, pay-by-link and cash transactions across providers could unlock broad network effects and new cross-provider value chains.
Industry Implications
-
Retail Banking — Banks that integrate omnichannel rails may see disruptions to branch economics through lightweight, distributed access points and partner-led customer acquisition.
-
Money Transfer and Remittance — Remittance operators combining cash-out networks with digital rails are positioned to reshape pricing, speed and inclusion for migrant and unbanked populations.
-
Retail and Convenience Stores — Merchants that host payment-agnostic services could evolve into neighborhood fintech nodes offering financial services alongside traditional retail goods.
3.9
Score
Popularity
Activity
Freshness